
Capital Allowances When Buying Commercial Property
Buying a commercial property can create a valuable Capital Allowances opportunity, but the position should ideally be established before the purchase completes.
The Capital Allowances available to a purchaser can be affected by the property’s tax history, claims made by previous owners and the treatment of fixtures within the transaction. In some circumstances, action may be required before completion or within specific statutory time limits to preserve the allowances available.
Blue Dawn Commercial works with purchasers and their professional advisers to investigate the Capital Allowances position, identify potential opportunities and highlight issues that should be addressed as part of the acquisition process.
Why Consider Capital Allowances Before Completion?
What Should Be Established Before Completion?
Capital Allowances Due Diligence
Blue Dawn can review the available property and transaction information to establish the Capital Allowances position before completion.
This can include reviewing the seller’s Capital Allowances information, CPSE replies, previous claims, proposed Section 198 elections and relevant transaction documents, helping to identify potential issues while there is still an opportunity to address them.
Section 198 Elections: What Buyers Need to Know
When purchasing a second hand commercial property, a Section 198 election may be required to agree the value of qualifying fixtures transferring from the seller to the buyer for Capital Allowances purposes.
The figure agreed matters. It can determine the amount on which the purchaser is able to claim Capital Allowances for the fixtures covered by the election.
Be Careful Before Agreeing a £1 Election
Section 198 elections are sometimes proposed at a nominal value of £1. However, £1 is not an automatic or statutory value that must be accepted.
Before agreeing an election, the purchaser should understand what the seller has previously claimed, what qualifying expenditure has been pooled and what Capital Allowances may otherwise be available.
Agreeing a nominal value without first establishing the position could significantly restrict the Capital Allowances passing to the purchaser.
The Election Is Irrevocable
Once a valid Section 198 election has been made, it cannot simply be changed later because the purchaser subsequently discovers that a different value would have been more beneficial.
This makes it particularly important to consider the Capital Allowances position before agreeing the election.
There Is Normally a Two Year Time Limit
A Section 198 election will normally need to be made within two years of the purchaser acquiring the property.
However, the existence of a two year time limit should not be treated as a reason to leave the issue until after completion. Once the property has been purchased, the buyer may have considerably less commercial leverage to negotiate the treatment of the fixtures with the seller.
Where possible, the Capital Allowances position and any proposed Section 198 election should therefore be considered as part of the acquisition process.
Don’t Leave Capital Allowances Until After Completion
Capital Allowances can easily become a small part of a much larger property transaction. For the purchaser, however, the treatment of qualifying fixtures can affect the tax relief available for years after the acquisition.
Establishing the position before completion provides an opportunity to identify potential allowances, raise appropriate enquiries and ensure that any Section 198 election is considered as part of the overall transaction rather than simply being dealt with afterwards.
WORKING WITH YOUR ADVISERS
Working Alongside Your Solicitor and Accountant
Capital Allowances can sit between tax, property and legal advice, which means important issues can sometimes be overlooked during a commercial property transaction.
Blue Dawn Commercial works alongside your existing solicitor and accountant, providing specialist Capital Allowances input where it is needed without replacing the advice they already provide.
We can help review the Capital Allowances information supplied by the seller, consider responses to Commercial Property Standard Enquiries (CPSEs), identify where further information may be required and provide input on the treatment of qualifying fixtures and any proposed Section 198 election.
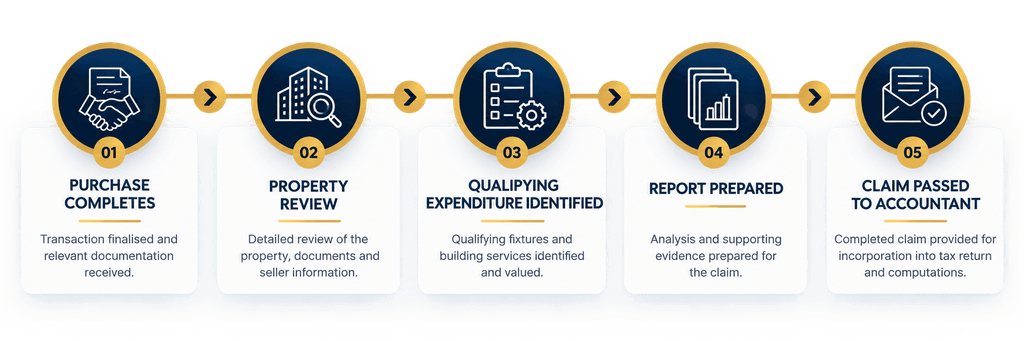
Where a potential Capital Allowances opportunity is identified, we can also undertake the specialist work required to establish and document the qualifying expenditure following acquisition.
WORKING WITH YOUR ADVISERS
Property enquiries, transaction documents and Section 198 provisions
WORKING WITH YOUR ADVISERS
Tax history, previous claims and incorporation of the eventual claim
WORKING WITH YOUR ADVISERS
Specialist review, Capital Allowances due diligence and valuation of qualifying expenditure
Buying a Commercial Property?
Capital Allowances are best considered before the transaction completes, while there is still an opportunity to establish the position, raise enquiries and address any issues with the seller.
If you are purchasing a commercial property, Blue Dawn Commercial can undertake an initial review of the proposed acquisition and help identify whether further Capital Allowances investigation is worthwhile.
Already completed your purchase? We can also review recently acquired and existing commercial properties to identify potential unclaimed Capital Allowances.